

Can Chapter 7 Help With Credit Card Debt, Medical Bills, and Personal Loans in Maryland?
Debt has a way of piling up quietly. One missed payment turns into three. A medical bill lands in your mailbox after a hospital visit you never planned for. Before long, you’re juggling calls from collectors and wondering if there’s a way out. Chapter 7 bankruptcy help in Maryland exists for exactly this kind of situation, and it works faster than most people expect.
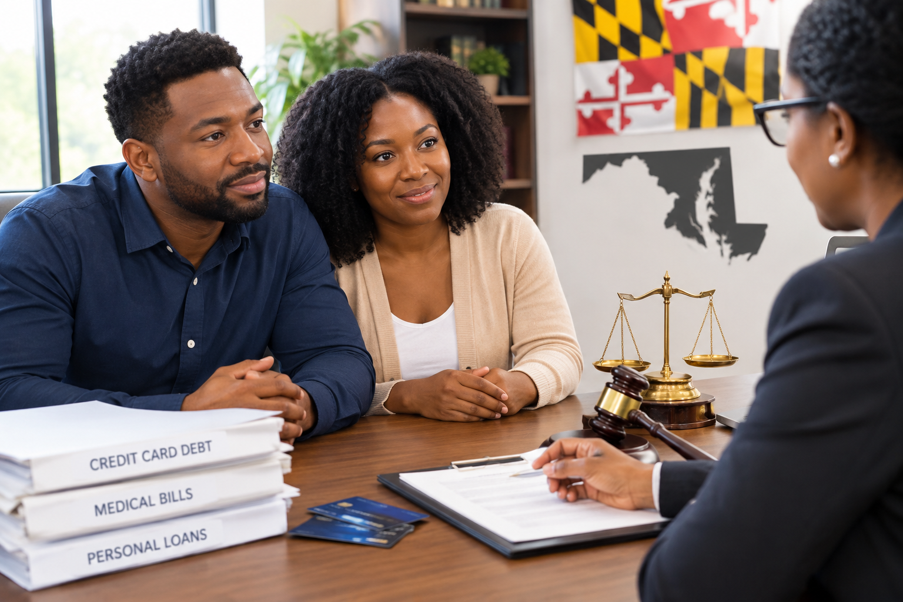
This guide walks through how Chapter 7 handles credit card debt, medical bills, and personal loans. We’ll also cover who qualifies, what the process looks like, and what this type of bankruptcy cannot erase.
What Chapter 7 Bankruptcy Actually Does
Chapter 7 is sometimes called “liquidation bankruptcy.” That sounds scary, but here’s what it really means. A court-appointed trustee reviews your assets and debts. In most cases, Maryland exemptions protect things like your car, household items, and retirement accounts, so you keep what you need. The main goal of Chapter 7 is simple. It wipes out unsecured debts so you can rebuild your finances without that weight following you around.
Does Chapter 7 Clear Credit Card Debt?
Yes, in most cases. Credit card balances are considered unsecured debt, meaning there’s no property tied to them as collateral. Chapter 7 typically discharges this debt completely once your case closes. That means the balance disappears. Collectors can no longer call you about it, and it stops showing up as an active debt you owe.
What About Medical Bills?
Medical debt is one of the most common reasons people look into bankruptcy. The good news is medical bills fall under unsecured debt too. Chapter 7 discharges them the same way it handles credit cards. This matters because medical debt often builds up fast. A single emergency room visit or surgery can leave someone owing thousands of dollars almost overnight. Chapter 7 gives a real path to clear that balance.
Personal Loans and Chapter 7
Personal loans without collateral, like many online lender loans or loans from family financing companies, are also unsecured. These generally qualify for discharge under Chapter 7 as well. If your personal loan is secured by property, such as a car title loan, the rules work a bit differently. You may need to give up the collateral or work out a separate arrangement to keep it.
Who Qualifies for Chapter 7 in Maryland?
Not everyone automatically qualifies. Maryland residents must pass something called the means test. This test compares your household income to the median income for a household your size in Maryland.
Here’s how it breaks down:
- Income below the median – You typically qualify for Chapter 7 without further steps.
- Income above the median – The court looks more closely at your monthly expenses and debts to see if you truly cannot repay them.
The means test exists so Chapter 7 stays reserved for people who genuinely need it.
What Happens After You File
Filing Chapter 7 involves a few clear steps. Knowing them ahead of time makes the process feel far less overwhelming.
- Credit counseling course – Required before filing. It takes about an hour and can be done online.
- Prepare your petition – This includes your assets, debts, income, and financial records from the past two years.
- File with the court – Maryland cases go through either the Baltimore or Greenbelt division, depending on where you live.
- Automatic stay begins – The moment you file, creditors must stop calling, garnishing wages, or pursuing foreclosure.
- Trustee review – A trustee checks your paperwork and confirms which property, if any, is not protected by exemptions.
- 341 meeting of creditors – A short hearing, usually about a month after filing, where the trustee asks questions under oath.
- Financial management course – A second required course, separate from the first one, completed before discharge.
- Discharge order – The court eliminates your qualifying debts, usually around three to four months after filing.
Each step builds on the last, and most people move through the entire process without ever setting foot in a courtroom.
What Chapter 7 Won’t Erase
Chapter 7 is powerful, but it has limits. Certain debts stay with you even after discharge. These include student loans, recent tax debt, child support, and alimony. Knowing this upfront helps set realistic expectations. A good attorney will walk through your full financial picture and explain exactly what relief you can expect.
Local Support Matters
Bankruptcy law includes state-specific rules, and Maryland is no exception. Working with an attorney in Bladensburg, MD means getting guidance shaped around local court procedures and exemption laws, not generic advice. The same goes for finding experienced bankruptcy attorneys in Hyattsville, MD. Local knowledge often makes the difference between a smooth filing and one full of delays.
FAQs
Q: Does Chapter 7 bankruptcy clear credit card debt in Maryland?
Ans: Yes. Credit card debt is unsecured, so Chapter 7 typically discharges it fully, freeing you from monthly payments and collection calls tied to that balance.
Q: Can medical bills be discharged through Chapter 7?
Ans: Yes. Medical debt counts as unsecured debt, so it usually qualifies for full discharge, just like credit card balances and most personal loans.
Q: How long does Chapter 7 stay on a Maryland credit report?
Ans: Chapter 7 typically stays on your credit report for ten years, though many people see their credit score start improving well before then.
Q: What debts can’t be discharged in Chapter 7?
Ans: Student loans, recent tax debt, child support, and alimony usually cannot be discharged. An attorney can confirm how these apply to your specific case.
Q: How much does Chapter 7 bankruptcy cost in Maryland?
Ans: Costs vary by case, but filing fees are set by the court. Many people qualify for payment plans or fee waivers based on income.
Ready to Talk Through Your Options?
If debt has been keeping you up at night, you don’t have to carry it alone. We have spent years helping Maryland families understand their choices and find real relief from overwhelming bills. At Joy Robinson Law Firm, we sit down with you, look at your full financial picture, and explain exactly what Chapter 7 can do for your situation. Reach out today, and let’s figure out your next step together.